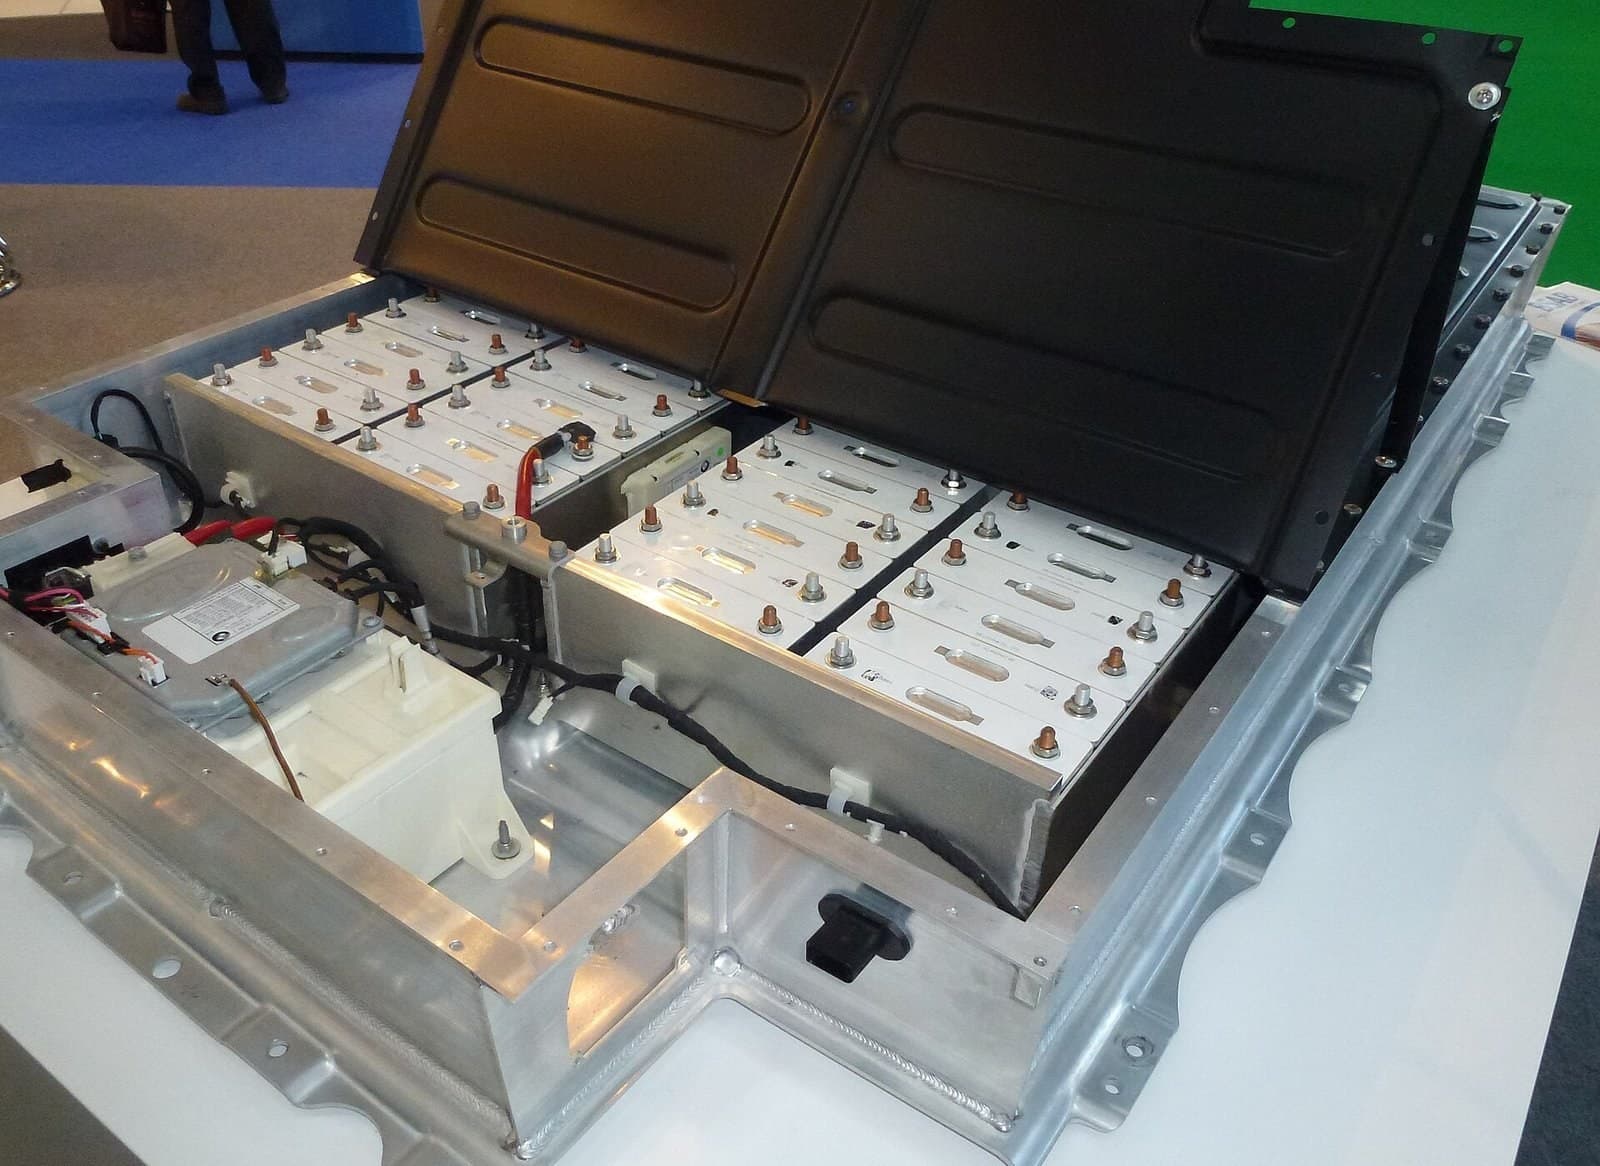
The battery is the part of the energy transition you can put on a scale and price by the kilogram, which makes it the easiest part to keep score on. BloombergNEF's 2025 survey reads: global average pack price $108 per kilowatt-hour, down 8% in a year to a record low, despite rising lithium and cobalt prices1. Beneath the average sit the regional averages that matter: China at $84, North America 44% above it, Europe 56% above it1. These are averages across many producers and chemistries, not any single factory's cost sheet, and the gap is not a rounding error. At a typical 60-kilowatt-hour car, it is the difference between a $5,000 battery and an $8,000 one, before anyone's tariff, repeated in every grid tender and fleet order on earth.
Beneath the geography sits the chemistry. Lithium-iron-phosphate packs, the cobalt-free, cheaper, heavier design that Chinese makers industrialised while Western chemistry stayed loyal to nickel, averaged $81 per kilowatt-hour against $128 for nickel-manganese-cobalt1. And beneath the chemistry sits the year's most startling line: packs for stationary storage, the grid batteries that make solar usable after dark, fell 45% in a single year to $70 per kilowatt-hour1.
China's average battery pack price in 2025. North America ran 44% higher and Europe 56% higher; the global average was $108.
Where the gap comes from
The premium has boring causes, which is why it is durable. Scale: Chinese plants run at volumes that amortise everything better, inside an ecosystem where cathode, anode, separator, and electrolyte suppliers sit within trucking distance. Vertical integration: the leaders own their materials chains back to the refinery. Competition: a brutal domestic price war, run at manufacturing overcapacity, that bankrupts the inefficient and reprices everyone's contracts annually1. Western plants buy imported equipment, train first-generation workforces, and ramp at yields their Chinese rivals passed a decade ago. Energy, labour, and subsidies differ too, but teardown studies keep finding that scale and integration explain most of the gap. None of that is fixed by a tariff, which changes who pays the gap, not whether it exists.
Concentration compounds the cost story. CATL and BYD together installed 659.5 gigawatt-hours of EV batteries in 2025, 55.6% of the world's total2; Chinese firms as a group hold about 69% of the global market2. The second tier, Korea's LG, Samsung SDI, and SK, holds most of the rest and builds the majority of what Western plants produce, often with Chinese equipment inside. A vehicle industry that spent a century mastering engines has discovered that its new core component has two dominant suppliers, both subject to Beijing's export licensing, an instrument already used on gallium and graphite.
The decade of history behind the number explains why forecasters keep being wrong in the same direction. When this survey began in 2010, packs cost over $1,000 per kilowatt-hour, and sober analysts doubted $300 was reachable; the 2022 materials squeeze produced the series' single price rise and a chorus declaring the curve broken. It resumed the following year. Fifteen years of roughly 90% decline is Wright's Law doing what it does when a product is manufactured in exponentially growing volume, and the only serious forecasting error left is treating any given year's price as a floor.
What the falling line buys
Every $10 off the pack price moves the crossover point where an electric drivetrain undercuts a combustion one without subsidy, and $84 in China explains what Western showrooms make mysterious: why Chinese EVs are cheap, why they hold majority shares of their home market, and why their exports terrify every legacy manufacturer with a cost sheet. The $70 stationary pack does the same work for grids, which is why storage deployment broke records on three continents in 2025 and why the 'what about nighttime' argument against solar is being retired by procurement departments rather than debaters1.
The 2025 survey also settled a nervous question: whether the battery-materials spike of 2022 would prove that pack prices cannot fall through commodity cycles. Metals rose in 2025; pack prices fell anyway, because materials are a shrinking share of a cost structure that manufacturing efficiency keeps compressing1. The learning curve has, so far, outrun every input shock thrown at it.
Segment | Price per kWh | Change |
|---|---|---|
Global average pack | $108 | -8% |
China average | $84 | -13% real |
North America | About 44% above China | -4% |
Europe | About 56% above China | -8% |
LFP packs, all segments | $81 | Cheapest chemistry |
NMC packs | $128 | |
Stationary storage packs | $70 | -45% |
BEV packs | $99 | Cheapest transport segment |
The demand mix is quietly rebalancing too, in ways the vehicle-centric coverage misses. Stationary storage was a niche outlet for cells five years ago; at $70 a kilowatt-hour it became the fastest-growing segment in the survey, price-elastic in a way car buyers are not, because a grid battery's business case is a spreadsheet with no brand loyalty in it1. Cheap cells create storage demand, storage demand absorbs the overcapacity that made cells cheap, and the loop has so far kept the factories of the price war fed even as EV growth disappointed the most optimistic projections. Markets with a second buyer of last resort crash differently from markets with one.
The Western dilemma, priced
The gap puts a number on the choice every Western capital is making with tariffs and subsidies: how much premium, paid by whom, for how long, buys a domestic battery industry worth having? The answers are uncomfortable in both directions. Buying Chinese packs at $84 maximises the speed and minimises the cost of electrifying, at the price of dependence on a duopoly a rival government licenses. Building domestic packs at $130-plus, behind walls, taxes every car buyer and grid ratepayer to fund a learning curve that may never intersect the leader's, as Europe's Northvolt bankruptcy demonstrated at scale. The compromise most governments are converging on, Chinese and Korean plants onshore, with local labour and imported know-how, is the same bet Morocco made with Gotion and America made with its licensing deals: import the learning curve rather than the product.
The tariff arithmetic, run in full, shows why the walls keep rising anyway. A 100% tariff on a $84 Chinese pack prices it at $168, comfortably above the domestic alternative, which is the point; it also means the domestic industry's target price is now the tariffed price rather than the world price, which is the problem. Protection that anchors local producers to a doubled benchmark buys existence at the cost of ambition, and the gap the wall conceals compounds outside it: every year of 13% Chinese declines against 4% domestic ones widens the distance the wall must eventually justify. Tariffs are a tourniquet, and the patient still needs the operation, which is a manufacturing system, not a border price.
There is also a security case that survives the cost arithmetic. Batteries are infrastructure: the packs stabilising grids and, increasingly, powering military platforms are components a state may rationally refuse to single-source from a strategic rival at any discount. The chip war produced export controls on machines; a battery war would produce controls on cells and the lithium-processing chemistry behind them, and Beijing has already demonstrated, on graphite and gallium, that it reads the dependency map the same way. Paying the premium for a second source is insurance pricing, and the only dishonest version of the policy is the one that pretends the premium is temporary.
For resource states, the pack price is the demand signal that disciplines everything upstream. Cheap packs mean the lithium, nickel, and phosphate markets grow through every price war their producers inflict on each other; the $70 stationary pack in particular opens a second demand engine that did not meaningfully exist five years ago. The mine owners' pricing power and the pack makers' cost curve pull against each other, and so far the cost curve is winning.
One prediction embedded in the price sheet is social rather than industrial. At $70 a kilowatt-hour and falling, battery-plus-solar becomes the default first electricity system for the parts of the world the grid never reached, the way the mobile phone became the default first telephone. The countries that skipped landlines are positioned to skip central generation for meaningful slices of their demand, buying their power system by the container from the same factories that supply Shenzhen. The price war's collateral beneficiary is everyone who was never going to be able to afford the old model, and that channel barely registers yet in the demand forecasts.
What to watch
Three numbers for 2026. The China pack price, because $84 falling further would say the price war has room left and every Western business case needs re-running again1. The regional premium, because convergence, if it ever starts, will show up as Western prices falling faster than Chinese ones, and its absence is the annual verdict on localisation policy. And sodium-ion's first meaningful volumes, because the next chemistry, using no lithium at all, is being industrialised by the same companies at the same pace, and its arrival would do to lithium's suppliers what LFP did to cobalt's. The survey updates every December. For fifteen years it has embarrassed everyone who bet against the curve.
BloombergNEF, Lithium-ion battery pack prices fall to $108 per kilowatt-hour (December 2025), with Energy-Storage.news's summary: global average $108/kWh, down 8%; China $84/kWh, down 13% in real terms; North America and Europe 44% and 56% higher; LFP $81 against NMC $128; stationary storage packs $70, down 45%; BEV packs $99.