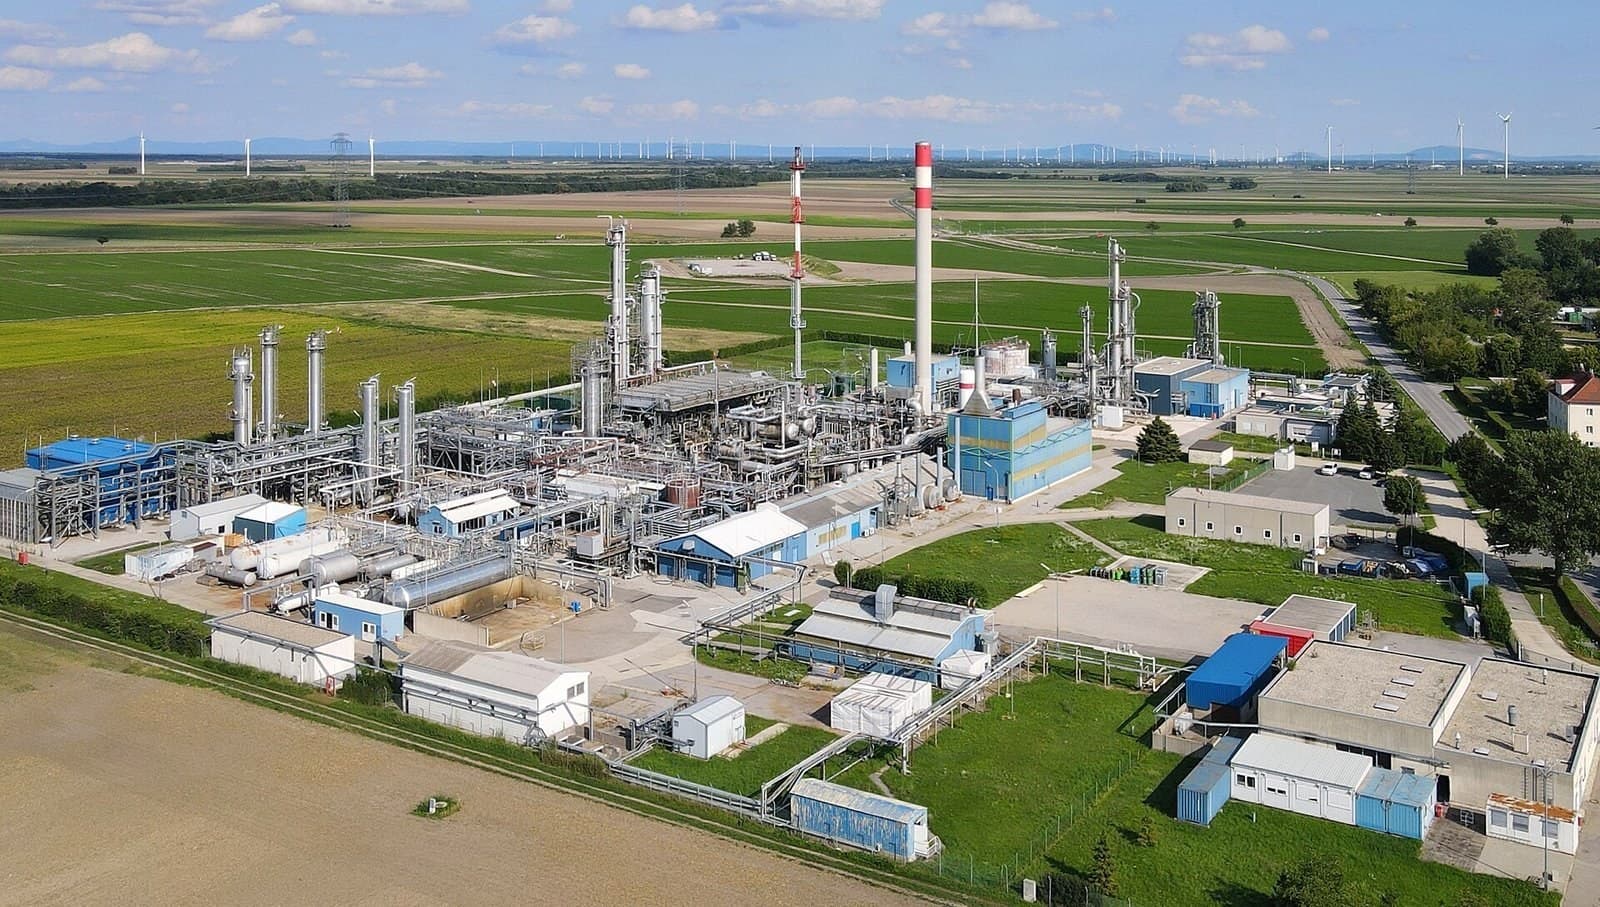
States do not usually abandon treasure. On 19 April 2024 the Netherlands did it by statute, legally and permanently closing the Groningen field, once Europe's largest gas deposit, with an estimated 550 billion cubic metres still recoverable1. At Dutch consumption of roughly 30 billion cubic metres a year, the country sealed about eighteen years of its own demand into the ground, in the middle of the decade Europe spent scrambling for every molecule it could find1.
The reason was under the residents' feet. Extraction compacted the sandstone reservoir, and the compaction produced earthquakes, more than a thousand of them over the field's life: shallow, and therefore damaging out of all proportion to their magnitudes, in a province of brick farmhouses never built for any seismicity at all2. The 2012 Huizinge quake turned complaints into a national question; a decade of caps, delays, and reversals followed; and a parliamentary inquiry that reported in 2023 concluded the state and its contractors had systematically put revenue above Groningers' safety. The closure law was the verdict's sentence.
Estimated gas remaining in the Groningen field at its permanent closure on 19 April 2024, about eighteen years of Dutch consumption.
Why small quakes broke a province
Groningen's earthquakes are physically modest, the strongest around magnitude 3.6, and structurally vicious, because induced seismicity cheats the usual scales. The events originate in the reservoir itself, about three kilometres down rather than the tens of kilometres of natural earthquakes, so their energy arrives concentrated under a small area; the province's soft clay soils amplify the shaking; and the housing stock, unreinforced masonry on a plain that had never shaken in recorded history, was engineered for wind and water, not ground motion. A magnitude that Tokyo would not notice cracks a Groningen farmhouse from gable to foundation. Repeat that a thousand times across two decades, add insurers and inspectors disputing each crack's cause, and the damage stops being structural and becomes civic: people whose houses were never quite whole and never quite condemned, waiting on assessments, for years.
What sixty years built and broke
Slochteren's discovery in 1959 rebuilt the postwar Dutch state. Groningen gas heated most homes in the country, seeded the national grid and the export contracts that supplied Germany, Belgium, and France, and filled the treasury so reliably that economists coined 'Dutch disease' for what the windfall did to the rest of the economy. The operator, NAM, a Shell-ExxonMobil joint venture, earned the supermajors on the order of 65 billion euros over the field's life2. The gas was low-cost, adjacent to demand, and politically frictionless for half a century, which is precisely why the friction, when it came, took the form it did: a community that had absorbed the damage while the money flowed elsewhere, discovering it had the votes.
The damage account is still open. The reinforcement and compensation programs run to tens of billions of euros, with some 22 billion euros allocated for the region in the wake of the inquiry3; tens of thousands of claims have been processed and thousands of houses reinforced or rebuilt, years behind schedule. In November 2024 NAM withdrew from funding the damage program, arguing the premature closure changed its obligations, leaving the state to carry the escalating cost2. And the ground has not finished: compaction lags extraction, so the region still shakes, now over a closed field, which is the cruellest detail in the whole affair.
The political anatomy repays study because it inverted the usual sequence. The state did not respond to the 2012 turning point by cutting output; production in the year after Huizinge was among the field's highest, because 2013 was a cold year and the contracts were the contracts. The caps came later, ratcheted down through a decade of court rulings, safety-board reports, and ministerial reversals, each cut promised as final and none believed. What ended the field was the accumulation of broken assurances as much as broken gables: by the time the inquiry reported, no cap short of zero had any credibility left to spend. Institutions that spend trust to buy time should note the exchange rate Groningen established.
The lawsuits after the funeral
The corporate endgame moved to arbitration. Shell and ExxonMobil have pursued investor-state claims against the Dutch government over the closure and over who bears the earthquake liabilities, in proceedings whose confidentiality is itself a political issue in a country that thought it had closed the chapter democratically4. Whatever the tribunals decide, the episode has become Europe's reference case for a question the energy transition will pose repeatedly: when a state ends an extractive concession early for its citizens' sake, who pays for the machine that was built to run longer?
The field's reach also complicated the exit for half a continent. Groningen gas is low-calorific, and decades of exports built an L-gas appliance park across the Netherlands, northern Germany, Belgium, and into France: millions of boilers and cookers tuned to one field's chemistry. Winding down Groningen meant converting whole national grids to high-calorific gas region by region, a programme of years that had to finish before the taps could close. The closure date the politics demanded and the closure date the pipework allowed spent a decade negotiating with each other, which is a detail worth remembering whenever an energy asset looks simple to switch off.
Living without it
The supply-side consequence was absorbed with less drama than feared, at a price. The Netherlands replaced Groningen and lost Russian pipeline gas in the same few years, becoming Europe's third-largest LNG importer: 16.2 million tonnes in 2023, over 70% of it American5. Rotterdam and Eemshaven, a terminal built at speed on Groningen's own coast, turned the province that produced Europe's gas into a landing stage for Texan molecules. On security, the country traded a domestic field for dependence on the Atlantic LNG market; on price, the cheapest gas in Europe for the world spot price; and on climate, pipeline methane for shipped LNG with a heavier upstream footprint5. Nobody in The Hague pretends otherwise. The country judged the trade worth it, which is the point.
The emergency-reserve question refuses to die politely. Dutch research agencies have urged keeping the sealed field technically restorable as a last-resort reserve against import failure6, and every European supply scare reopens the argument. The law says closed; the wells are being cemented; and each winter's gas price decides how loudly someone asks whether 'permanent' has exceptions. So far the answer has held, earthquake risk does not respect emergencies, and restarting would reopen the exact wound the closure was meant to heal.
Year | Event |
|---|---|
1959 | Discovery at Slochteren; Europe's largest gas field |
2012 | Huizinge earthquake turns damage into national politics |
2013 | Production near its highs even as complaints mount |
2014-2022 | Successive caps ratchet output toward zero |
2023 | Parliamentary inquiry: interests of Groningers structurally ignored |
19 April 2024 | Closure by law; about 550 bcm left in place |
2024-26 | NAM exits damage funding; arbitrations proceed; region still shakes |
What Groningen proves
Three exportable lessons. Externalised costs compound politically even when they stay flat physically: the quakes did not grow, the province's patience ran out. Resource wealth without local benefit is a standing referendum that eventually gets held; petrostates and mining provinces elsewhere are running the same experiment with different vote counts. And energy security arguments lose to lived damage: the closure's final votes came after 2022, in the teeth of the strongest security case for domestic gas in fifty years, and the case lost.
The counterfactual is worth a paragraph, because the closure's critics are not wrong about the arithmetic. Five hundred and fifty billion cubic metres, sold into the tightest gas market in European history, was worth on the order of a decade of Dutch defence budgets; produced carefully at low rates, some engineers argued, it could have funded the reinforcement of every house in the province many times over. The province had heard 'careful' and 'low' before, which is why the counterfactual, however priced, was never politically available: the currency it required, believable assurance, had already been spent.
Watch three things from here. The arbitration outcomes, which will price every future early closure in Europe4. The pace of the reinforcement program against its promises, because the state inherited the obligation it once shared. And the reserve debate each winter, because it measures, in real time, exactly how much energy insecurity a rich democracy will absorb to keep a promise to a province. Sixty-five years after Slochteren, the field's last export is the precedent: proof that a state can find gas, build a nation on it, and, when the ground demands it, choose to stop. Every extractive region watching its own damage accumulate now knows the ending can be negotiated.
Gas Outlook, Dutch Groningen gas field shuts down permanently, and JPT, Groningen gas field to shut down for good: legal closure 19 April 2024; remaining reserves estimated around 550 bcm against Dutch consumption near 30 bcm a year.
SOMO, Groningen gas field: the aftershock: over a thousand induced earthquakes; about 65 billion euros earned from the field; NAM's November 2024 withdrawal from funding the damage program.
Holland Times, Groningen receives 22 billion euros in compensation (2023).
Euronews, ExxonMobil sues Dutch government over gas field closure (October 2024), and Drilled, Exxon and Shell sue the Netherlands in secret tribunals.
Natural Gas Intelligence, Groningen field to permanently close as the Netherlands increases pipeline and LNG imports, and NL Times, Netherlands faces increased climate impact from US LNG imports: 16.2 million tonnes imported in 2023, over 70% from the US; third-largest European LNG importer.
NL Times, Research agency urges keeping Groningen gas field as emergency reserve (February 2026).